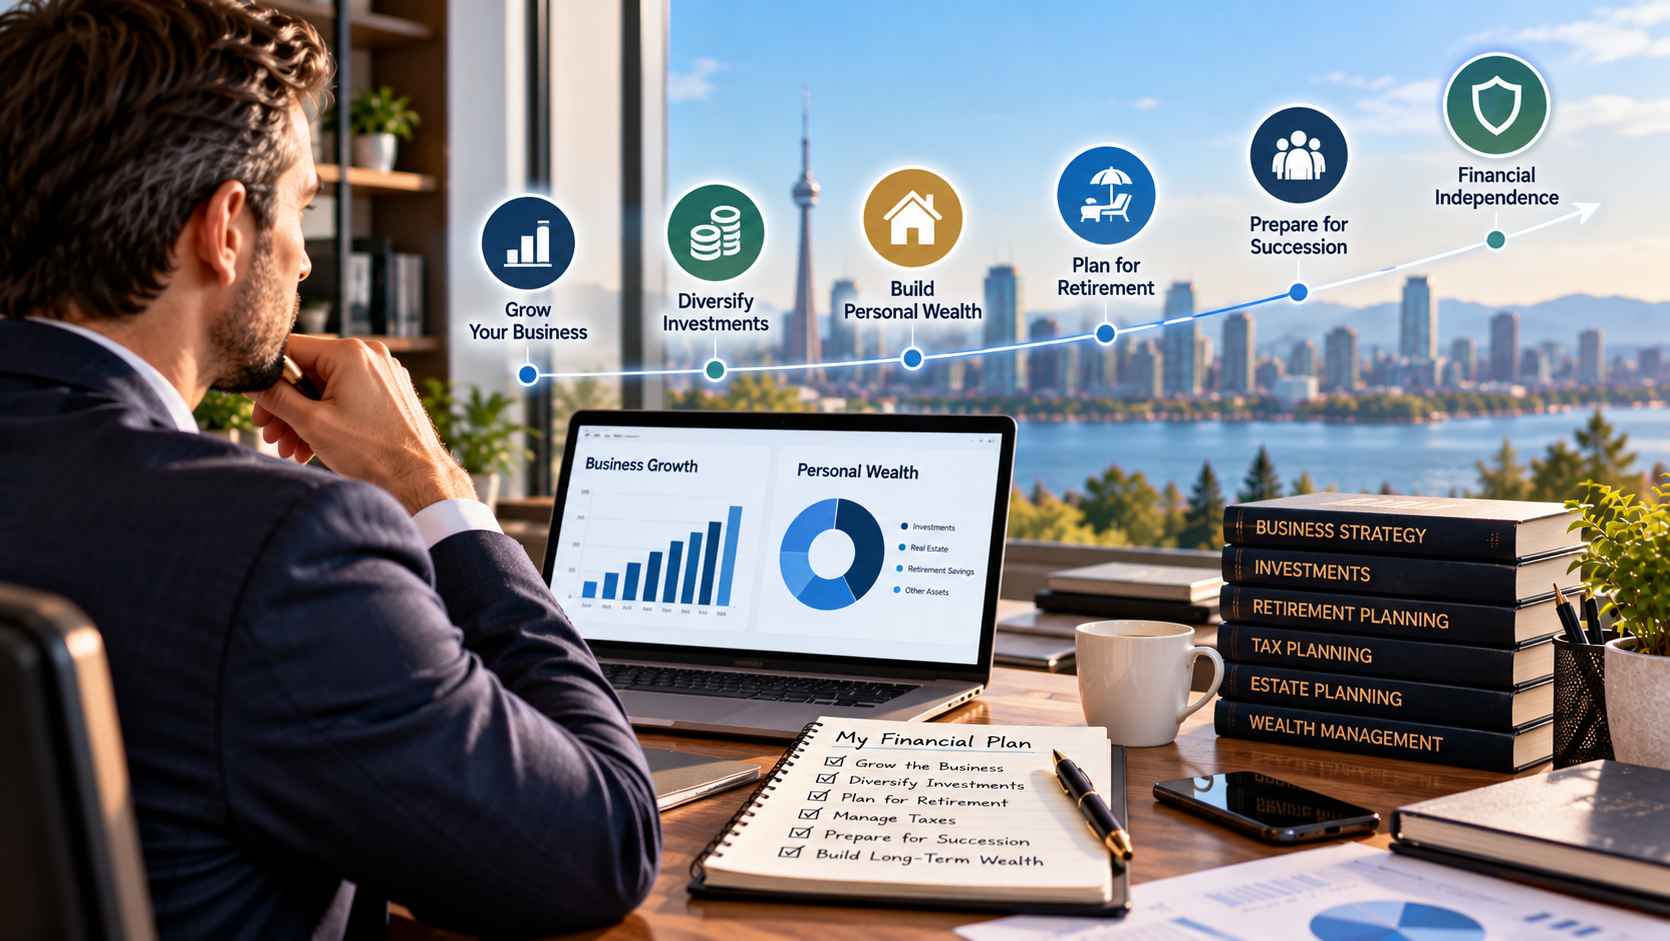
Building a successful business can create significant financial opportunity, but it can also create a unique planning challenge: much of the owner’s wealth may remain tied to the company.
For an entrepreneur, the business may represent income, savings, an investment, and eventually a potential source of retirement capital. That concentration can make it easy to postpone building financial security outside the company. As long as the business is growing, there may seem to be little reason to change course.
The difficulty comes when personal financial goals and business goals become too dependent on the same asset. Retirement timing, family needs, investment objectives, and future lifestyle plans can all become connected to what happens to the company.
Creating financial independence beyond the business does not mean taking attention away from entrepreneurship. It means making sure the owner’s long-term financial future does not depend entirely on one outcome.
Why Business Owners Can Become Financially Concentrated
Business owners often have a different financial profile from salaried professionals.
Instead of receiving a predictable employment income and gradually building a portfolio of investments, an entrepreneur may reinvest profits into employees, equipment, property, technology, marketing, or expansion. Personal wealth can therefore grow primarily through the value of the business itself.
That approach can make sense for a growing company, but it can also create concentration.
If most of an owner’s net worth is connected to one business, the financial future may be affected by factors outside the owner’s complete control. Industry conditions, competition, changing customer demand, economic conditions, management challenges, or an unexpected disruption can influence the company’s value.
The objective is not necessarily to reduce business investment immediately. Rather, it is to recognize that business wealth and personal financial security are not the same thing.
Separate Business Value From Personal Wealth
One of the first steps toward greater financial independence is understanding how much of the owner’s overall financial position is actually outside the company.
A business can have substantial value on paper without providing accessible personal funds for everyday needs, retirement, or unexpected expenses.
This distinction becomes particularly important when planning for major life stages.
For example, an owner may estimate that a future business sale will provide the capital needed for retirement. But the timing, structure, value, and tax treatment of a future transaction may not be known years in advance.
Building personal assets alongside the business can provide another layer of financial flexibility.
This may include maintaining appropriate cash reserves, contributing to retirement savings, investing outside the company, or gradually building other assets according to an individual’s circumstances and objectives.
Professional advice can help an owner examine these areas together. Exponent Investment Management works in wealth management and financial planning, providing an example of how business owners can consider personal wealth alongside broader financial objectives.
Build Investments Outside the Business
Diversification is not simply an investment concept. For a business owner, it can also be a way of separating personal financial security from the performance of the company.
When nearly all available capital remains inside one business, the owner may have limited exposure to other types of assets or sources of potential future income.
Building investments outside the company can gradually change that balance.
The appropriate mix depends on factors such as time horizon, financial objectives, liquidity requirements, tax circumstances, and tolerance for investment risk. There is no universal portfolio that works for every entrepreneur.
The broader principle is to avoid assuming that the business must remain the primary source of personal wealth forever.
An owner who gradually builds a separate pool of investments may have more flexibility later. That could affect decisions about retirement, reducing working hours, taking time away from the business, or accepting an acquisition offer.
Think About Retirement Before an Exit
Retirement planning for business owners can be complicated because the business may be part of the retirement strategy itself.
An entrepreneur might expect to sell the company at 60 or 65 and use the proceeds to fund retirement. Another owner may plan to transfer the company to family members or employees. Someone else may want to keep ownership but reduce their involvement in daily operations.
Each path can create different financial requirements.
A useful retirement plan therefore considers what life may look like without the same level of business income.
Questions can include how much income may be required, which assets could provide that income, how much liquidity is needed, and whether retirement depends on a particular business value or transaction.
The earlier these questions are considered, the more options an owner may have to adjust the strategy.
Prepare for Succession
Financial independence and succession planning are closely connected.
A business owner may eventually sell the company, transfer ownership to family members, bring in partners, sell to employees, or pursue another transition structure. Each possibility can affect both the company and the owner’s personal financial position.
The Government of Canada identifies succession planning as an important part of preparing Canadian businesses for ownership transitions and provides resources for entrepreneurs considering the sale or transfer of a business. Government of Canada business succession planning
Succession planning also raises questions beyond the transaction itself.
What happens to personal income after the transition? Will the owner still have sufficient investments outside the company? How might taxes affect the proceeds? Are family members expecting to receive business interests? Does the owner’s estate plan reflect the intended transfer?
These questions demonstrate why succession should not be treated as a single event at the end of an entrepreneur’s career.
Consider Tax and Long-Term Wealth Goals
Taxes can influence decisions throughout the business lifecycle, including how income is received, how investments are held, and how assets may eventually be transferred.
For business owners, tax planning may also intersect with retirement planning and succession decisions. The rules can depend on the business structure, ownership arrangements, type of transaction, province or territory, and individual circumstances.
That is why tax planning should be coordinated with qualified professional advice rather than treated as a last-minute consideration before an exit.
Long-term wealth goals should also extend beyond the business.
An entrepreneur may want to fund a particular lifestyle, support family members, make charitable contributions, purchase additional property, or leave assets to future generations. Those objectives can require planning well before the business transition occurs.
Review the Strategy as the Business Changes
A financial independence strategy should evolve as the business evolves.
A company that is rapidly expanding may require significant reinvestment. Later, the owner may reach a point where personal diversification becomes a higher priority. A major business acquisition, property purchase, change in family circumstances, or approaching retirement date can also alter the financial picture.
Regular reviews can help answer a simple question: Is the current balance between business wealth and personal wealth still appropriate for the owner’s goals?
This does not mean constantly changing investments or making decisions based on short-term business conditions. It means periodically reassessing whether the overall plan still reflects the owner’s priorities.
For entrepreneurs, financial planning for business owners can help connect business decisions with personal objectives such as retirement, investment diversification, succession, and long-term wealth creation.
Building Independence Without Losing Focus on the Business
A successful company can remain an important part of an entrepreneur’s financial future without being the only part.
Building assets outside the business, thinking about retirement before an exit becomes imminent, preparing for succession, and considering tax and estate issues can create a broader financial framework.
The goal is not to predict exactly when or how a business transition will happen. It is to create enough flexibility that the owner’s personal financial future is not entirely dependent on one eventual outcome.
Business growth may remain the entrepreneur’s primary focus for years. But alongside that growth, building personal financial security can provide another form of progress—one that continues to matter even when the next chapter of the business eventually begins.